X12 transaction guide · Finance
EDI 201 Residential Loan Application
The X12 document used to transfer the data of the Uniform Residential Loan Application between lenders and other parties.
- Sent by
- Mortgage lender or broker
- Received by
- Service vendors, insurers, credit agencies or investors
- Standard
- ANSI ASC X12
What is an EDI 201?
The EDI 201 Residential Loan Application is the ANSI X12 transaction set used to transfer the data contained in the Uniform Residential Loan Application between mortgage lenders, mortgage service vendors, insurance companies, credit reporting agencies and others.
The loan application is the core data set of a mortgage: borrower, employment, income, assets, liabilities, property and loan terms. Sharing it as data lets every party in the process start from the same information. The industry now generally exchanges application data in MISMO XML formats.
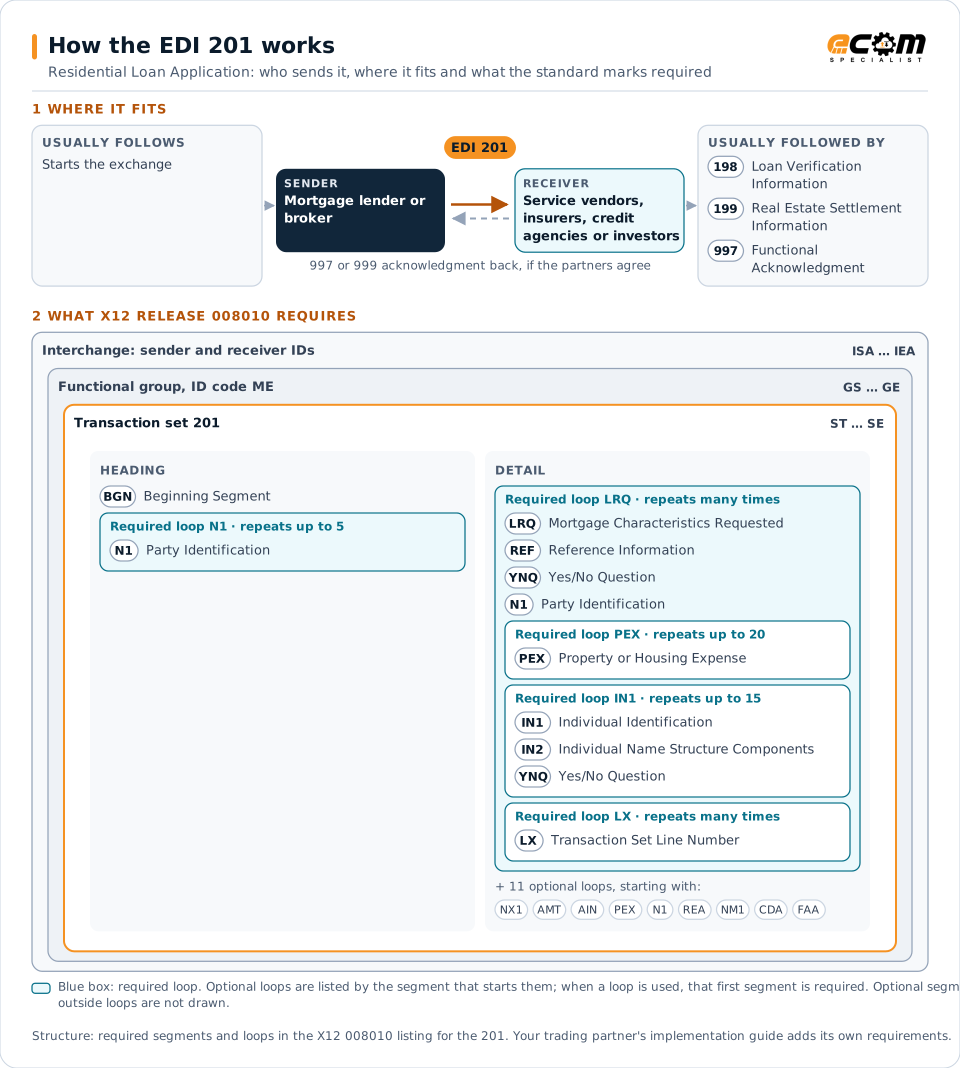
How to read this diagram: the top row shows who sends the 201, to whom, and which documents usually come before and after it. The lower part shows what X12 release 008010 itself requires: the envelopes around the 201 and the segments and loops the standard marks as required, area by area. Optional loops are listed by the segment that starts them rather than drawn in full. This is the standard's minimum, not a trading partner's requirement: each partner's implementation guide usually makes some optional loops mandatory, restricts the codes and may use a different release.
When it is used
- Sending applications from brokers to lenders
- Sharing application data with service providers
- Submitting applications for automated underwriting
Where it fits in the document flow
Structure
Mandatory segments in the 201 (X12 release 008010)
The segments X12 release 008010 marks as mandatory at their level, in order. Segments inside optional loops are needed only when the loop is used. This is the standard's requirement, not your trading partner's: each partner's implementation guide names the release it uses, adds the optional segments it requires and restricts the values. The requirement status comes from one published X12 reference listing and has not been checked against a second source.
- ST
- BGN
- N1
- LRQ
- REF
- YNQ
- NX1
- NX2
- PEX
- AMT
- IN1
- IN2
- AIN
- REA
- NM1
- CDA
- FAA
- LX
- SE
Practical example
The 201 in practice
A mortgage broker takes an application from a homebuyer. Its loan origination system sends the lender a 201 with the borrower's details, income, assets, debts and the property and loan requested. The lender loads the application and starts verifications without rekeying.
Implementation
Implementation considerations for the 201
- Check whether partners use MISMO XML instead of X12.
- Protect borrowers' personal and financial data.
- Keep the application data synchronized as it changes.
- Follow regulatory disclosure requirements.
How ECOM helps
Automate the 201 with ECOM
Industry
Financial Services
Secure file transfer and B2B integration for banks and financial institutions.
Solution
Financial Document Automation
Automate invoices, remittances, payment files and bank statements from capture to posting.
Solution
EDI Integration
Exchange X12 and EDIFACT documents with partners and integrate them directly with your ERP.
More general questions about EDI are answered in the EDI FAQ.
Related transactions
Related finance documents
- 198Loan Verification Information
- 199Real Estate Settlement Information
- 139Student Loan Guarantee Result
- 144Student Loan Transfer and Status Verification
- 191Student Loan Pre-Claims and Claims
- 202Secondary Mortgage Market Loan Delivery
- 264Mortgage Loan Default Status
- 820Payment Order/Remittance Advice
- 135Student Aid Origination Record
- 155Business Credit Report
- 197Real Estate Title Evidence
- 200Mortgage Credit Report
Need help with the EDI 201?
ECOM maps, tests and monitors X12 documents for your trading partners and integrates them with your ERP.